Your search dashboard can look healthy while the budget decision remains unresolved. Paid search claims conversions, organic search receives assisted credit, and AI-search referrals appear in GA4 when referral data survives. Then finance asks the question the dashboard cannot answer: how much revenue would disappear if you stopped?
Choosing another attribution model will not settle that question. You need two connected systems: an evidence chain that follows search activity into realized revenue, and a causal test that estimates what search created rather than merely touched. Here is how to build both without pretending the data is cleaner than it is.
Attribution assigns credit; incrementality tests causation
Attribution asks which observed touchpoints should receive credit for a conversion. Incrementality asks whether the conversion happened because of the marketing activity. Those are different questions, and they support different decisions.
Consider a customer who already intends to buy, searches for your brand, clicks a paid result, and completes the purchase. An attribution model may give the ad full or partial credit because the click is visible. An incrementality test asks how many comparable customers would have purchased without being eligible to see that campaign.
This distinction matters most when a channel sits close to conversion. Branded Search can collect a large amount of credited revenue without necessarily creating an equally large amount of new demand. Performance Max can span several Google properties, making channel-by-channel paths harder to interpret. For eligible Search and Performance Max campaigns, user-based Conversion Lift creates an unexposed holdout and compares its behavior with that of users who can be exposed. The difference estimates incremental conversions.
That does not make attribution useless. Attribution helps you reconcile customer journeys, diagnose tracking, allocate observed credit, and identify where conversions are being captured. It becomes misleading only when credited revenue is presented as revenue caused.
Key takeaways
- Use attribution to describe observed paths and allocate credit; use incrementality to make causal budget claims.
- Connect search activity to realized revenue before debating which attribution model deserves the final click.
- Keep unknown and unattributed revenue visible instead of forcing every conversion into a channel.
- Run a controlled test when the causal answer could change a meaningful spending decision.
- Report attributed and incremental results side by side. Never substitute one for the other.
Build the revenue trail from the business outcome backward
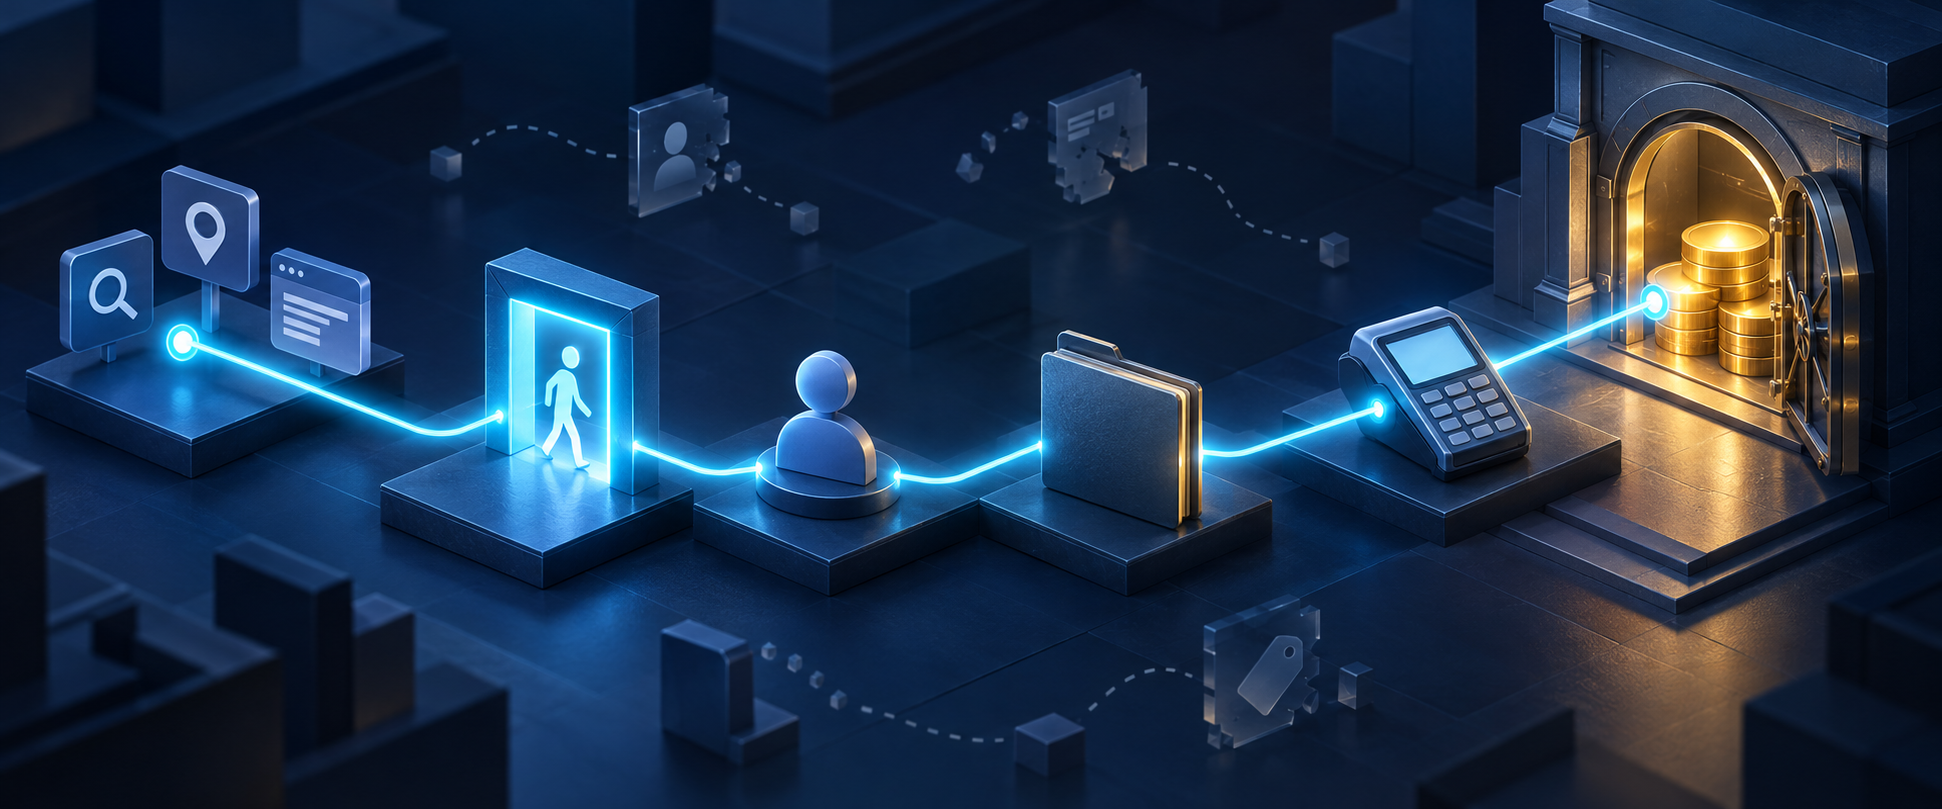
A reliable measurement plan begins with the outcome your organization recognizes as revenue. It does not begin with the easiest event in GA4 or the conversion a media platform happens to optimize.
- Define the commercial outcome. For ecommerce, decide whether the recognized value is the completed order, collected payment, or revenue after refunds and cancellations. For lead generation, distinguish a submitted form, qualified lead, opportunity, and closed-won sale. Write down the event, its valuation method, and the point at which it becomes reportable revenue.
- Capture acquisition evidence. Store campaign parameters for links you control, along with the landing page, referrer when available, and timestamp. Add a self-reported discovery question when the buying journey can begin in an AI answer, an untagged result, or another environment that may not pass referral data. Keep the self-reported answer separate from the machine-captured source.
- Preserve the first and subsequent touches. Do not overwrite the original source every time a person returns. Retain the initial discovery evidence, the most recent measurable interaction, and relevant intermediate touches so that later analysis can distinguish demand creation from conversion capture.
- Carry a stable record into the revenue system. Use an approved internal transaction or lead identifier to connect analytics activity with the order platform or CRM. Avoid relying on names or email addresses as analytical keys when a privacy-safe internal identifier is available.
- Reconcile to realized value. Join the record to the value finance recognizes. Document how you treat duplicates, reopened opportunities, cancellations, refunds, repeat purchases, and records that never match.
- Measure coverage. Report the share of conversions with a known acquisition source, the share of revenue successfully matched to a transaction or CRM record, and the amount left unknown. A visible unknown bucket is more trustworthy than invented precision.
AI search makes this discipline especially important. When an AI answer does not pass a referrer or tracked link, a later direct visit cannot reveal the earlier discovery by itself. Self-reported discovery can provide supporting evidence, but it should not silently replace behavioral data. Treat agreement between the two as corroboration and disagreement as a reason to inspect the journey.
A workable AI-search revenue program puts GA4 setup, a five-level attribution ladder, and a board-ready scorecard in the same measurement system. Traffic collection without revenue reconciliation stops too early. A revenue total without source coverage hides too much.
Use a five-level ladder to prevent signal inflation
Search teams often mix visibility, visits, conversions, and revenue in one report even though each represents a different level of evidence. A five-level ladder keeps those claims separate.
- Visibility. Rankings, impressions, mentions, citations, or other forms of search presence show that your brand or content can be discovered. They do not establish that a person visited or bought.
- Visits. Sessions, referral data, campaign parameters, and landing-page activity show measurable traffic. They still do not prove that the visit produced a qualified outcome.
- Qualified outcomes. A business-defined action such as a qualified lead or valid purchase separates meaningful demand from raw activity. The definition must be stable enough to compare across channels.
- Attributed revenue. Transactions or closed-won revenue matched to observed search interactions show where measurable credit appears. The attribution model determines how that credit is distributed.
- Incremental value. A controlled comparison estimates the additional conversions or revenue caused by the marketing activity. This is the level needed for a causal return claim.
Apply one rule throughout the report: a metric keeps the label of the highest level its evidence actually supports. Do not multiply AI-search visibility by an average conversion rate and present the result as measured revenue. That calculation may be useful as a forecast or scenario, but it remains modeled value and should be labeled accordingly.
The same rule applies when you change attribution models. Moving from one credit-allocation method to another can redistribute attributed revenue among touchpoints. It cannot promote the result from attributed revenue to incremental value. A different model changes the accounting view, not the counterfactual.
For each channel, ask what prevents the evidence from moving to the next level. Missing campaign parameters block clean visit classification. An analytics-to-CRM gap blocks revenue matching. A lack of controlled variation blocks causal inference. This turns the ladder into a measurement backlog rather than a decorative maturity score.
Run an incrementality test when the answer can change spend
Incrementality testing has a real cost. A holdout withholds campaign exposure from some users, and those users may generate fewer conversions. Use the method when the result can change a material decision: whether to retain, reduce, expand, or restructure a campaign.
Self-serve Google Ads Conversion Lift has explicit eligibility gates for Search and Performance Max. An advertiser needs at least 1,000 observed conversions, excluding conversions that use supplementary data; participating campaigns need a minimum budget of $5,000; and the account needs at least one compatible conversion action. Availability can still vary by account, and alpha or beta campaign types may require assistance from a Google representative.
Meeting those gates does not guarantee a decisive result. The selected action must occur frequently enough to be statistically useful. Purchases, leads, website activity, and other eligible actions can be evaluated, but the action you choose should correspond as closely as possible to the decision you need to make.
- Write the decision first. State which campaign and budget choice the result will inform. A test without a decision attached tends to become an interesting chart rather than an operating tool.
- Choose one primary outcome before launch. Define the eligible conversion action and how it maps to revenue. If the action is a lead rather than a sale, keep the test result in incremental leads until you have a defensible lead-to-revenue mapping.
- Set the campaign scope. Include the campaigns needed to answer the question and avoid mixing unrelated budget decisions into the same test.
- Accept the holdout tradeoff explicitly. A larger holdout can improve the comparison sample, but it also withholds ads from more users. Record who accepted that opportunity cost and why it is proportionate to the decision.
- Keep the plan stable. Avoid changing the primary outcome, campaign scope, or interpretation rule after seeing an early result. If operations force a material change, document it rather than presenting the test as untouched.
- Translate the output only as far as the evidence allows. Report incremental conversions directly. Convert them to incremental revenue only through an agreed value mapping, then connect that revenue to margin if the budget decision is based on profit.
Keep two efficiency calculations distinct:
- Attributed ROAS = attributed revenue divided by advertising spend.
- Incremental ROAS = incremental revenue caused by the advertising divided by advertising spend.
Attributed ROAS can be much higher than incremental ROAS when a campaign captures conversions that were likely to happen anyway. That does not automatically mean the campaign has no value. It means its budget case should be made with incremental economics rather than the full amount of credited revenue.
If you are not eligible for the platform test, do not turn a before-and-after chart into causal proof. A carefully designed geographic or phased-rollout test may provide a comparison when you can maintain a credible control and consistent measurement. If you cannot create that comparison, report attributed performance and state plainly that the incremental effect has not been measured.
A board-ready scorecard shows the decision, not just the dashboard
Executives do not need every touchpoint row. They need to see what is observed, what is inferred, what is causal, how much of the revenue trail is covered, and what decision follows.
| Scorecard line | What to show | Question it answers | Required label or caveat |
|---|---|---|---|
| Attributed revenue | Realized revenue allocated to measurable search interactions | Where did observed credit appear? | Name the attribution method and reporting scope |
| Incremental outcome | Additional conversions or revenue estimated by a valid control comparison | What did the campaign cause? | Show the tested campaigns, primary outcome, and uncertainty provided by the test |
| Measurement coverage | Source-known conversions, revenue-matched records, and unknown revenue | How complete is the evidence chain? | Do not redistribute the unknown bucket |
| Economics | Spend, attributed ROAS, incremental ROAS when available, and the finance-approved value basis | Is the activity economically useful? | Keep attributed and incremental returns separate |
| Decision | Scale, retain, reduce, retest, or repair measurement | What changes because of this result? | Name the owner and the condition that would reverse the decision |
Read the combinations, not just the largest number:
- High attributed revenue and credible positive lift: the channel is receiving credit and creating additional outcomes. Evaluate whether incremental economics support more investment.
- High attributed revenue and weak or uncertain lift: the channel may be capturing existing demand. Do not use the credited total as proof that the same revenue would vanish with the spend.
- Low attributed revenue and poor measurement coverage: the result is inconclusive. Repair source capture and revenue matching before treating the channel as ineffective.
- Attribution changes sharply when the model changes, while experimental lift remains stable: the disagreement is primarily about credit allocation, not whether the campaign caused additional outcomes.
- No credible control comparison: keep the causal field marked as not measured. A blank causal result is more useful than a confident answer produced by the wrong method.
In your next reporting cycle, add two lines to every search performance review: “What revenue can we trace?” and “What revenue did we cause?” If the second answer is unavailable, do not replace it with modeled certainty. Mark it as not yet measured, identify the live budget decision it affects, and plan the smallest credible control test around that decision. This prevents credited revenue from being mistaken for created demand.
References
- HiGoodie — AI Search Revenue Attribution Guide [+ Free PDF]
- Search Engine Land — Google opens Conversion Lift to Search and Performance Max

Leave a Reply